Many people start Social Security at 62 and keep working part-time or full-time. It is a common plan, and it is allowed. But there is one rule that surprises people every year: the Social Security earnings limit 2027.
Thank you for reading this post, don't forget to subscribe!
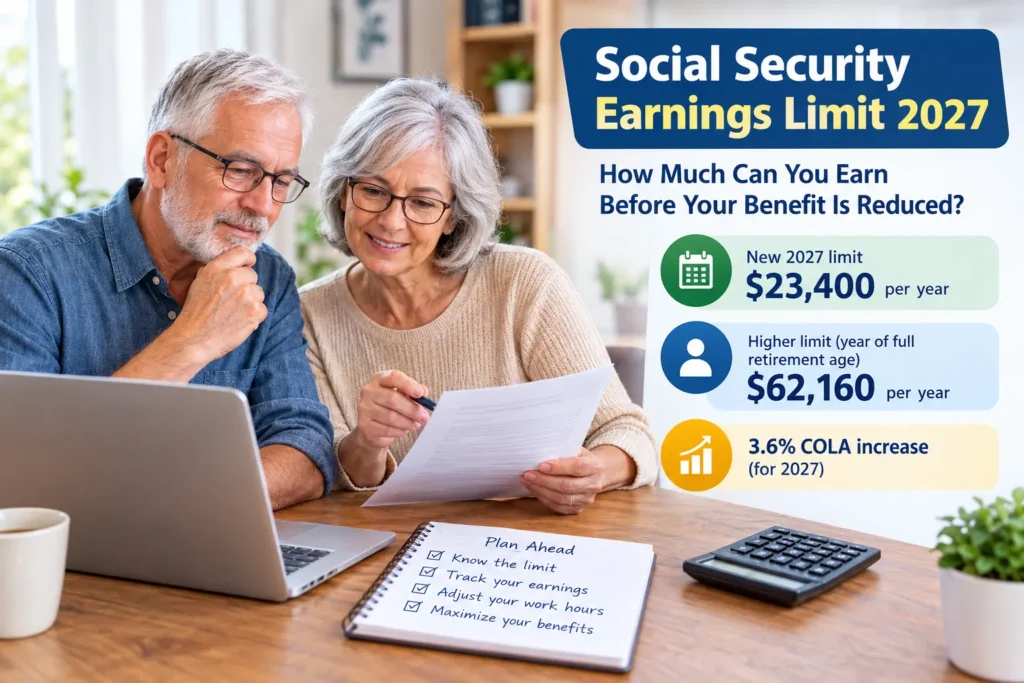
If you are younger than full retirement age and earn more than the limit, the Social Security Administration (SSA) holds back part of your benefit. The agency announced the new 2027 limits on October 14, 2026, along with a 3.6 percent cost-of-living adjustment.
This guide explains the new numbers in plain English, shows how the reduction works with real examples, and covers what to do if you are close to the limit.
What Is the Social Security Earnings Limit 2027?
The earnings limit, also called the retirement earnings test, applies when you collect retirement or survivors benefits before your full retirement age (FRA) and still have a paycheck or self-employment income.
If your work earnings stay under the yearly limit, nothing changes. If they go over, SSA withholds part of your benefit for that year.
Full retirement age is 67 for anyone born in 1960 or later. For people born earlier, it is slightly lower. You can check yours on the SSA full retirement age chart.
The 2027 Earnings Limits at a Glance
SSA publishes two different limits, depending on where you are in relation to full retirement age.
| Your Situation | 2026 Limit | 2027 Limit | What Is Withheld Above the Limit |
| Under full retirement age all year | $24,480 per year | 25,560peryear(2,130 per month) | $1 for every $2 earned over the limit |
| The year you reach full retirement age | $65,160 per year | $67,920 per year | $1 for every $3 earned over the limit |
| Full retirement age or older | No limit | No limit | Nothing is withheld |
In the year you reach full retirement age, SSA counts only the earnings you make in the months before the month you reach it. Earnings after that month do not count.
You can confirm these figures on the official SSA COLA information page.
What Counts as Earnings and What Does Not
This is where many people worry for no reason. SSA counts only income from work.
Counted toward the limit:
- Wages from a job, including bonuses, commissions, and vacation pay
- Net profit if you are self-employed
Not counted toward the limit:
- Pensions and annuities
- Investment income and interest
- Veterans benefits
- Other government or military retirement benefits
So a retiree with a pension and a rental or savings income can still stay well under the limit if the paycheck itself is small.
How the Reduction Works: Two Simple Examples
These are made-up examples to show the math. Your own numbers will differ.
Example 1: Under Full Retirement Age All Year
Maria is 63 and collects 1,200amonth(14,400 a year). She works part-time and earns $33,560 in 2027.
- Her earnings are $8,000 over the $25,560 limit.
- SSA withholds $1 for every $2 over, which is $4,000.
- She receives $10,400 of her $14,400 in benefits for that year.
Example 2: The Year You Reach Full Retirement Age
David turns 67 in September 2027 and collects $2,000 a month. He earns $75,000 from January through August.
- His earnings are $7,080 over the $67,920 limit.
- SSA withholds $1 for every $3 over, which is $2,360.
- Starting the month he reaches full retirement age, nothing more is withheld, no matter how much he earns.
Your Withheld Benefits Are Not Lost
This point is often missed. Money withheld under the earnings test is not taken away for good.
When you reach full retirement age, SSA recalculates your monthly benefit to give you credit for the months in which benefits were reduced or withheld. In practice, you get a higher monthly check later.
Working can also help in another way. SSA reviews earnings records every year, and if your latest year of earnings is one of your highest, your benefit may be recalculated upward.
The earnings limit is still a real cash-flow issue. If you need the full amount every month, a reduced check now can be hard even if it is made up for later.
The First-Year Special Rule
If you retire mid-year and have already earned more than the annual limit, there is a special rule that helps. For one year only, SSA pays a full benefit for any whole month you are considered retired, no matter what you earned for the year.
This is a detail worth asking SSA about if you retire partway through 2027. It can make a big difference in your first year.
Step-by-Step: Check Whether the 2027 Limit Affects You
Step 1: Find Your Full Retirement Age
Look up your FRA using your birth year. If you will reach it before the end of 2027, the higher $67,920 limit applies to you for the months before that date.
Step 2: Estimate Your 2027 Work Earnings
Add up expected wages or net self-employment profit. Leave out pensions, investments, and interest.
Step 3: Compare It With the Right Limit
Use $25,560 if you are under FRA all year. Use $67,920 if you reach FRA during 2027.
Step 4: Use the SSA Earnings Test Calculator
SSA offers an official earnings test calculator that shows how your earnings could affect your payments.
Step 5: Report Changes to SSA
If your expected earnings change during the year, tell SSA. Reporting a pay raise, a new job, or a drop in hours helps avoid overpayments or surprises later.
Step 6: Review Your Budget Before the Year Starts
If part of your benefit may be withheld, plan for it. Our guide on how a simple budget review can help retirees is a good place to start.
Real-Life Scenarios
The part-time worker. A 64-year-old works 20 hours a week at a garden center and expects to earn about $18,000. That is under the limit. No benefits are withheld.
The consultant. A 65-year-old earns $42,000 a year from consulting and also receives a small pension. Only the consulting profit counts. Since it is above $25,560, part of the benefit will be withheld, and the pension does not change that math.
The person turning 67 mid-year. A worker turns 67 in July, earns $50,000 before then, and plans to keep working. Because the $67,920 limit applies, no benefits are withheld, and after July there is no limit at all.
Do’s and Don’ts
Do
- Check your full retirement age before you claim
- Estimate your yearly work income early in the year
- Tell SSA when your earnings change
- Use official SSA tools and your my Social Security account for exact numbers
- Consider speaking with a licensed financial professional if your situation is complex
Don’t
- Don’t count pension or investment income toward the limit
- Don’t assume withheld benefits are gone forever
- Don’t guess your earnings and hope for the best
- Don’t use unofficial websites for exact benefit amounts
Common Mistakes to Avoid
- Confusing the two limits. The $25,560 limit and the $67,920 limit apply to different situations.
- Using last year’s numbers. The 2026 limits were $24,480 and $65,160. Both go up in 2027.
- Assuming the rule applies after full retirement age. It does not. Once you reach FRA, there is no limit.
- Forgetting about self-employment. Net profit from a side business counts as earnings.
- Ignoring taxes. Depending on your combined income, up to 85 percent of Social Security benefits may be taxable. Our guide on how retirees can legally reduce taxes after 60 explains the basics.
- Claiming early without a plan. If you expect to keep earning above the limit, think carefully before claiming. Our article on the best age to claim Social Security walks through the trade-offs.
Other 2027 Social Security Numbers Worth Knowing
The earnings limit is announced together with several other yearly adjustments. According to SSA:
- COLA: Benefits rise 3.6 percent starting in January 2027. SSA says the average retirement benefit will rise by about $75 per month. See our full guide on the 2027 Social Security COLA.
- Taxable maximum: The amount of earnings subject to Social Security payroll tax rises from $184,500 to $192,300. This matters mostly for people who are still working and earning well.
- Disability work threshold: For people on disability benefits, the substantial gainful activity level rises to 1,770permonth(2,950 if blind). Disability benefits follow different rules than the retirement earnings test.
Your personal COLA notice should be available in your my Social Security account starting in late November, or by mail in December.
Work-Related Scam Warning
Whenever Social Security makes news, scammers follow. Some callers claim your benefits will be suspended because of “unreported work income” and ask you to confirm your Social Security number or pay a fee to fix it.
SSA does not demand payment by gift card, wire transfer, or cryptocurrency. If you get a call or text like this, do not respond. Hang up and contact SSA through its official website or phone number. Our guide on Social Security phone scams every retiree must know covers the warning signs in detail.
When to Contact the Social Security Administration
Reach out to SSA if:
- You are unsure which earnings limit applies to you
- Your income changes during the year
- You retire mid-year and want to know whether the special first-year rule applies
- Your payment is lower than expected
- You think you received a suspicious message that claims to be from SSA
You can call SSA at 1-800-772-1213, visit a local office, or sign in to your my Social Security account.
This article is for general education only. It is not personalized financial, tax, or legal advice. Your situation may be different, so confirm details with SSA or a licensed professional.
Frequently Asked Questions
What is the Social Security earnings limit for 2027?
If you are under full retirement age all year, the limit is $25,560. In the year you reach full retirement age, the limit is $67,920 for the months before you reach it.
What happens if I earn more than the limit?
SSA withholds $1 in benefits for every $2 you earn above $25,560, or $1 for every $3 above $67,920 in the year you reach full retirement age.
Do I lose the withheld money permanently?
No. When you reach full retirement age, SSA recalculates your benefit to give you credit for the months in which benefits were reduced or withheld.
Is there an earnings limit after full retirement age?
No. Beginning with the month you reach full retirement age, your work earnings do not reduce your benefits, no matter how much you earn.
Does my pension count toward the limit?
No. SSA does not count pensions, annuities, investment income, interest, veterans benefits, or other government retirement benefits. It counts only wages and net self-employment income.
Can I work while collecting Social Security at 62?
Yes. You can work at any age while collecting benefits. At 62, though, you will fall under the lower limit, so earnings above $25,560 in 2027 may lead to withheld benefits.
Conclusion
The Social Security earnings limit 2027 is higher than last year, which helps people who work while collecting benefits. The key is knowing which limit applies to you and what counts as earnings.
Take ten minutes to estimate your 2027 work income, compare it with the right limit, and use SSA’s official calculator for a clear answer. With that information, you can decide whether to keep working, adjust your hours, or rethink when to claim.
If you are exploring part-time options, our list of best jobs for people over 55 with no degree may give you some ideas. And to see how your income, savings, and spending fit together, try our retirement calculator.